With DSCR (debt-service coverage ratio) loans, real estate investors can qualify for financing based on a property's ability to pay its debt obligations with its rental income. They don’t have to worry about their personal income, employment history, tax returns, or debt-to-income ratio.
That makes them a good option for buying rental properties if you're self-employed, carry a high debt-to-income ratio, write off most of your income, or otherwise don't qualify for conventional loans.
Those benefits aside, the DSCR lender you choose still matters. It determines how quickly you can close, how easy it is to qualify, how much you need to put down, and whether you will face last-minute complications before closing.
In this article, we cover four factors to consider before choosing a DSCR lender, then we compare 10 DSCR lenders against those factors, starting with our own DSCR loans at Constitution Lending.
Note: Since Constitution Lending is our company, we've aimed to keep this comparison fair to every lender on the list. That said, borrowers choose us because we close most loans in 7 to 14 days and have no DSCR minimums. To see the rates and terms you qualify for, run your deal through our DSCR loan pricer for an instant quote, term sheet, and pre-approval letter.
Factors to Consider Before Choosing a DSCR Lender
1. Do they offer automated tools to speed up the application process?
Closing speed matters most because it determines whether you can compete with cash buyers for undervalued properties. When we were investing ourselves, we often found good deals before anyone else, then lost them to faster cash buyers because our lender couldn't close in time.
But we also don't recommend taking a lender's advertised closing time at face value. It’s common for lenders to promise to close in 10 or 15 days, for example, and then take more than a month.
A reliable way to figure out a lender’s true closing speed is to look at how quickly they send you quotes, term sheets, and pre-approval letters. These are the simplest documents to produce, so a lender that needs days to issue them likely has slow, bureaucratic internal processes that won't speed up once underwriting starts.
Look for lenders that offer automated pricing tools that can issue a quote, term sheet, and pre-approval letter on the same day you apply. This is a strong sign that the lender prioritizes speed, which is likely to carry through to the closing process.
2. Do they have real estate investing experience?
This is something most borrowers don’t consider, but we advise working with DSCR lenders who have experience investing in real estate because it can make a big difference in whether you end up qualifying.
Many loan officers and underwriters don’t know how to evaluate a deal from a real estate investor’s point of view. Instead, they run your deal through an underwriting algorithm and decide based almost entirely on the DSCR it produces. That leaves little room for human judgment, so it’s common for strong deals with great potential to get rejected.
For example, a multifamily property with high vacancy might fall below most lenders' DSCR minimums, even if you bought it under market value and can fill the units within a few months. An algorithm sees a low ratio and declines it, while an experienced investor sees the upside.
That’s why we recommend working with lenders whose team has real estate investing experience. They can judge whether a deal makes sense and are more willing to approve deals that don't fit the rigid requirements of other lenders.
3. Are they a direct lender or a broker?
We don’t recommend working with brokers because they don't fund loans but rather pass your application to a separate lender whose underwriters make the final decision.
That's why brokered deals often fall apart late in the process. A broker may tell you early on that you qualify based on their read of your deal, but the actual lender only decides after fully underwriting your file. If that lender finds an issue the broker missed, you can be rejected days before closing, after your earnest money is already committed.
A direct lender funds loans with its own capital and makes every decision in-house. Because the team reviewing your file is the same team approving it, you get a definitive yes or no early on.
4. What are their qualification requirements?
Every DSCR lender sets its own minimum DSCR and maximum loan-to-value ratios (LTV), so the same deal can qualify with one lender and get declined by another.
- Minimum DSCR. DSCR compares a property's monthly rent to its monthly debt payment, including principal, interest, taxes, insurance, and any HOA dues. A ratio of 1.0 means the rent exactly covers that payment. Many lenders require at least 1.0, while others accept ratios as low as 0.75 or set no minimum, usually in exchange for a lower LTV or a higher rate.
- Maximum LTV. Most DSCR lenders finance up to 80% of the purchase price, which means a 20% down payment, and up to 75% on cash-out refinances. A few go higher for borrowers with strong credit.
Check both requirements, along with the lender's minimum credit score, before you apply. That way you'll know whether your deal qualifies before you spend time or money on an application.
10 DSCR Lenders Compared
1. Constitution Lending: Fast Funding Built to Help You Compete with the Speed of Cash Buyers
Constitution Lending is a Connecticut-based direct lender offering DSCR loans to real estate investors (both first-time and seasoned investors).
We founded Constitution Lending after countless bad experiences with lenders. We’ve been investing in real estate for several years and understand how slow most lenders are. Many promised to close in a week or two, but then took over a month. This cost us millions of dollars in undervalued real estate.
We designed Constitution Lending to help borrowers close fast enough to compete with cash buyers, and to fix the other problems we ran into as investors.
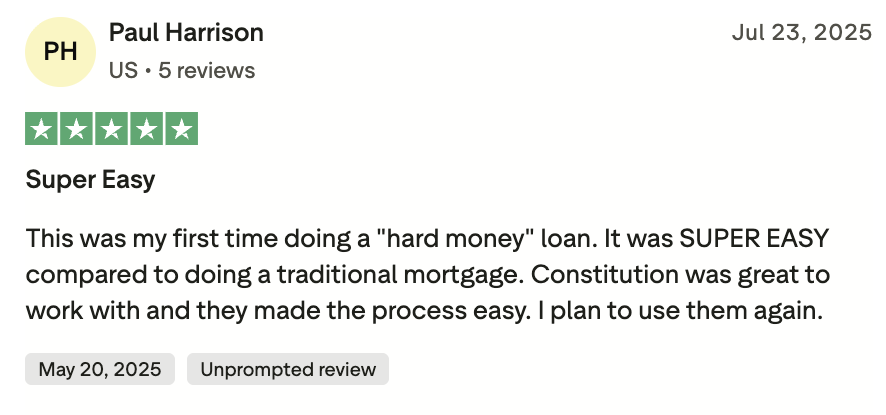
Here’s what borrowers say about our speed and reliability:


Below, we discuss how Constitution Lending addresses the factors above.
Get Same-day Quotes, Term Sheets, and Approval Letters and Close Within 7 to 14 Days
As we mentioned earlier, many lenders use inefficient, manual processes to move your loan from initial submission to closing.
For example, your application may wait in a queue for days before a loan officer reviews it. Then a loan officer has to call you to walk through the deal before they'll send a quote. You may also have to send documents back and forth over email for weeks instead of uploading them in one place.
At Constitution Lending, we use automated tools and processes like our loan pricer and documents portal to close faster than other lenders. Here’s how it works:
- Enter a few details into our loan pricer (e.g., the state your property is in, what type of property you’re looking to purchase or refinance, and your credit score), and it’ll generate three quotes:
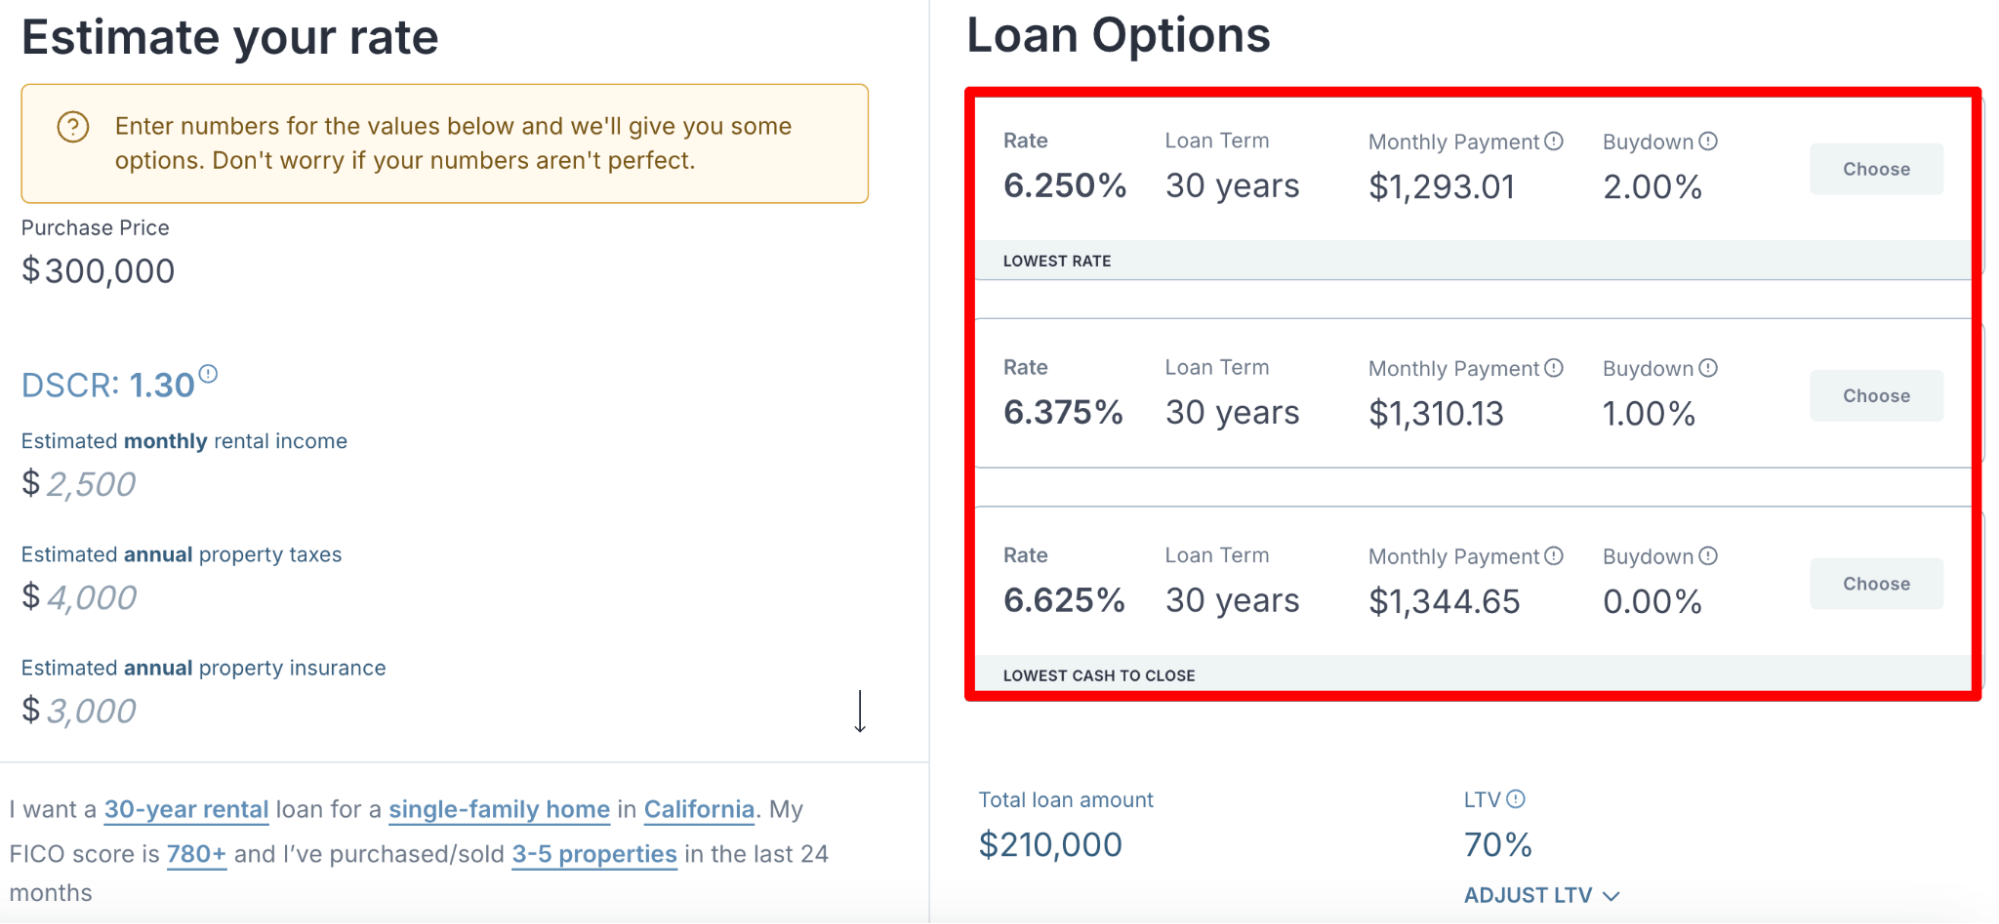
- From here, you can tweak your LTV and purchase price to see how it affects your interest rates, DSCR, and monthly repayments. If you like one of our quotes, click on it, enter your contact details, and you’ll receive a term sheet and pre-approval letter immediately.
- After that, we send you access to our documents portal, where you can submit the necessary paperwork, and we’ll fund the loan within one to two weeks.

- In scenarios where borrowers have all the documentation ready and need a loan urgently, we’ve closed DSCR loans within four days.
You can compare our speed to lenders like LendingOne, Griffin Funding, and Visio Lending, which report closing times of 14 to 21 days, 34 days, and 30 days, respectively.
We Evaluate Your Deal Like Real Estate Investors, Not a Lending Algorithm
Before we started lending, we spent years buying and managing rental properties ourselves.
This experience as real estate investors allows us to review every application the same way we evaluate our own deals. We look at the property's overall profitability and whether the deal makes sense rather than traditional underwriting criteria.
That lets us be more flexible with our criteria. For example, a multifamily property with high vacancy often doesn't generate enough rent to meet most lenders' DSCR minimums. If you bought it below market value and the units can realistically be filled, we look at what the property will earn once it's leased up and can fund the loan even when the current DSCR falls short.
We Are a Direct Lender, Meaning No Last-Minute Rejections or Complications
Constitution Lending is a direct lender, meaning we’re financing your loan. We aren’t brokers who’re connecting you with the actual lender.
The benefit of this is that we know exactly what our loan requirements are and can guarantee closing as soon as you submit the required documents. We won’t come back to you at the last minute with a rejection letter like brokers so often do.
Read more: DSCR Loan Pros and Cons: A Detailed Guide for Investors
Our DSCR Loan Requirements
Our requirements focus on the property, not your personal finances:
- Minimum DSCR: None
- Maximum LTV: up to 80% on purchases and 75% on refinances
- Minimum credit score: 660
- Loan amounts: $150,000 to $3 million
- Cash reserve requirements: none required
- Income verification: no tax returns, W-2s, or pay stubs
- Eligible properties: single-family homes, 2 to 4-unit properties, 5 to 20-unit buildings, and condos
- Loan terms: 30-year fixed, with interest-only financing options available
- Prepayment penalties: flexible step-down options
- Borrowing entity: individuals or LLCs
- Short-term rentals: Eligible
- Where we lend: all 50 states
Get Fast, Low-Interest DSCR Financing with Constitution Lending
Generate an instant quote using our DSCR loan pricer and we’ll send you a pre-approval letter and term sheet immediately.
2. LendingOne
Founded in 2014 and based in Boca Raton, Florida, LendingOne has funded more than $11 billion in loans for real estate investors. It lends in every state except Alaska, Nevada, North Dakota, and South Dakota, and its DSCR program is built for investors scaling rental portfolios, including those following a BRRRR strategy.
Speed: LendingOne doesn't have a public pricer that generates instant quotes or term sheets. Its "See Your Rate" button leads to the same page as "Apply Now," and the site points borrowers to a loan advisor, so it's unclear what automation supports its stated 14 to 21 day average from prequalification to funding.
Underwriting approach: LendingOne describes its underwriting as flexible and focused on each property's cash flow, handled by teams that specialize in investment property loans. Lending expertise isn't the same as having bought and managed rentals yourself, though, so deals that depend on an investor's read of a property's potential may still be judged mainly on the numbers.
Direct lender: LendingOne funds its own loans, so the team reviewing your file is the one approving it. That gives you a clear answer early in the process, while you still have time to fix an issue or line up other financing.
Qualification: Minimum DSCR of 0.75, up to 80% LTV on purchases and 75% on cash-out refinances, and loan amounts from $85,000 to $2 million. Eligible properties include single-family rentals, 2 to 4-unit properties, condos, and townhomes, and short-term rentals may qualify. It lends in every state except Alaska, Nevada, North Dakota, and South Dakota.
3. Griffin Funding

Griffin Funding is a direct-to-consumer mortgage lender that has funded more than 2,100 DSCR loans totaling over $650 million, and DSCR loans now make up 40% of its volume. It's also one of the few DSCR lenders that holds state mortgage licenses and federal approvals for VA and FHA lending.
Speed: Griffin issues pre-approvals within 24 to 48 hours, but only after receiving a complete application and supporting documents. By the test in factor 1, that wait points to a longer process overall, and it lines up with Griffin's stated 34-day average closing time, even though its fastest DSCR loan closed in 6 days.
Underwriting approach: Griffin runs qualification through LIA, a proprietary AI platform that matches each borrower's profile to the best-fit loan program. That speeds up processing, but the decision centers on how your file fits Griffin's program guidelines rather than an investor's read of what the property can earn.
Direct lender: Griffin underwrites and funds its loans in-house, so the answers you receive come from the party actually approving the loan. If something in your file is a problem, you'll hear about it before you're deep into the process.
Qualification: No minimum DSCR, with a no-ratio program available, a minimum credit score of 620, and down payments from 15% for borrowers with 740+ credit. Loans go up to $4.5 million, borrowing through an LLC is allowed, and there's no cap on the number of properties you can finance.
Griffin is one of the most flexible lenders on this list when it comes to credit and DSCR requirements. If closing speed is your priority, though, Constitution Lending's 7 to 14 day timeline is roughly three weeks shorter than Griffin's average.
4. Kiavi

Kiavi is one of the largest non-bank lenders to residential real estate investors, and Figure Technology Solutions completed its $717 million acquisition of the company on September 1, 2026. The Kiavi brand and platform remain active, but its DSCR rental loans are now originated and funded by Figure Lending LLC.
Speed: Kiavi's online platform lets you check your rate without a hard credit pull, so it passes the quote test from factor 1. Third-party reviews put its DSCR closings at around 20 to 30 days, though, so the fast start doesn't fully carry through to funding.
Underwriting approach: Kiavi markets its DSCR loans as AI-powered. Automation brings speed and consistency, but it leaves less room for someone to weigh a deal's upside when the current numbers come up short.
Direct lender: You can apply with Kiavi directly online rather than through a broker. Since DSCR loans now come from Figure's lending arm, get your terms in writing before going under contract, because programs can shift while the two companies integrate.
Qualification: DSCR as low as 0.8 for eligible scenarios, up to 80% LTV, and loan amounts from $100,000 to $3 million. Kiavi lends in 49 states and Washington, D.C., with 30-year fixed, adjustable-rate, and interest-only options.
Kiavi makes it easy to see your numbers early. Constitution Lending pairs instant pricing with closings in 7 to 14 days, and our programs aren't going through an ownership transition.
5. Lima One Capital

Based in Greenville, South Carolina, Lima One Capital has financed real estate investors since 2011 and is backed by MFA Financial, a publicly traded real estate investment trust. Its rental program serves buy-and-hold investors with single-family and small multifamily properties.
Speed: Lima One keeps underwriting, appraisal management, and servicing in-house, which means fewer outside parties slowing the file down. Its rental loans close in about 21 days on average.
Underwriting approach: Lima One's minimum DSCR is 1.0, adjusted for borrower experience and property type. Approval is tied closely to current income, so a property with temporary vacancy may need to be leased up before it qualifies.
Direct lender: Lima One funds its own loans, so its approval comes from the same team that closes them. You'll know where your loan stands well before your closing date.
Qualification: Minimum DSCR of 1.0, up to 80% LTV on purchases and 75% on cash-out refinances, and loan amounts from $100,000 to $2.5 million.
Lima One is a dependable option for investors with stabilized rentals. If your deal depends on what the property will earn after lease-up, our investor-led underwriting can account for that potential, and we typically close a week or more sooner.
6. Visio Lending

Founded in 2012 in Austin, Texas, Visio Lending focuses exclusively on DSCR loans and was ranked the No. 1 DSCR lender in the country by Scotsman Guide based on 2024 volume. It has originated more than $4.2 billion in rental property loans.
Speed: Visio pulls credit and orders the appraisal when you apply, then works with title, insurance, and other third parties to build a complete file before approval. It aims to close within 30 days.
Underwriting approach: Visio describes its underwriting as common-sense, with a standard DSCR floor of 1.0. Ratios below that are reviewed case by case, so lower-DSCR deals are possible but not part of the standard program.
Direct lender: Visio approves and funds its own loans, but much of its volume comes through a network of more than 1,000 mortgage brokers. Applying with Visio directly gets you answers from the decision-maker instead of a broker relaying them.
Qualification: Standard minimum DSCR of 1.0, up to 80% LTV on purchases and 75% on cash-out refinances, and loan amounts starting at $75,000.
Visio's DSCR specialization is hard to beat for straightforward rentals. For investors racing cash buyers, Constitution's 7 to 14 day timeline is about half of Visio's 30-day target.
7. Angel Oak Mortgage Solutions
Angel Oak Mortgage Solutions is an Atlanta-based non-QM lender founded in 2013 that has originated more than $19 billion in loans. It's one of the largest wholesale lenders of non-QM loans in the country and offers its DSCR program, called Investor Cash Flow, alongside bank statements and jumbo loans.
Speed: Angel Oak uses a rental automated valuation model to set a property's DSCR upfront instead of waiting for a physical appraisal. That number is then locked for the loan unless something significant changes, which cuts down on surprises late in the process.
Underwriting approach: Because the rental valuation is automated, qualification leans on data models rather than an experienced investor's judgment about the property's potential.
Direct lender: This is where Angel Oak differs most from the rest of this list. It partners with mortgage brokers and correspondent lenders rather than lending to investors directly, so most borrowers reach it through a middleman, along with the late-rejection risk covered in factor 3.
Qualification: Minimum DSCR of 1.0 with a no-ratio option, up to 85% LTV with a 720+ credit score, and loan amounts from $100,000 to $3 million.
Angel Oak's range of non-QM programs suits borrowers with unusual financial profiles. If you'd rather deal directly with the people funding your loan, Constitution works with investors one-on-one, with no broker in between.
8. Easy Street Capital

Headquartered in Austin, Texas, and founded in 2016, Easy Street Capital is a private direct lender that has funded more than $3 billion in DSCR loans over the past four years through its EasyRent program, which covers long-term and short-term rentals.
Speed: Easy Street is best known for fast fix-and-flip closings, but its own DSCR page says rental loans close in as little as 30 days.
Underwriting approach: EasyRent has no minimum DSCR. Weaker ratios are offset with lower leverage or less favorable pricing, which keeps the door open for low-DSCR deals while pricing them by formula.
Direct lender: Easy Street lends its own capital and makes decisions in-house, so you hear directly from the team funding your loan.
Qualification: No minimum DSCR, up to 80% LTV on purchases and 75% on cash-out refinances, and loan amounts from $100,000 to $3.5 million.
Easy Street is a good fit for properties that fall below most lenders' DSCR minimums. When timing matters more, Constitution's 7 to 14 day closings run two to three weeks ahead of Easy Street's best-case rental timeline.
9. RCN Capital

Founded in 2010 and based in South Windsor, Connecticut, RCN Capital has originated more than $8.2 billion across over 37,000 loans. Its long-term rental program sits alongside fix-and-flip, bridge, and construction financing.
Speed: RCN is known for quick turnarounds on its short-term loans, including next-business-day term sheets. Ask for a term sheet on your rental deal early, since how fast it arrives is the best preview of how fast the rest of the loan will move.
Underwriting approach: RCN requires a minimum DSCR of 1.0 on long-term rental loans, so properties with vacancies or below-market rents generally need to be stabilized first.
Direct lender: RCN lends its own capital, but it describes itself as a nationwide wholesale lender and does a large share of its business through brokers. Applying directly means you hear from RCN's underwriters rather than a broker passing along their decision.
Qualification: Minimum DSCR of 1.0, up to 80% LTV on purchases and 75% on cash-out refinances, and loan amounts from $70,000 to $1.5 million.
RCN's low minimum loan amount suits investors buying lower-priced rentals. For larger deals, Constitution lends up to $3 million and works with borrowers directly from application to closing.
10. New Silver
New Silver is a technology-focused direct lender for real estate investors, with DSCR loans offered alongside fix-and-flip, bridge, and construction financing.
Speed: New Silver issues term sheets instantly online, so it passes the factor 1 test. Its DSCR loans typically close in 2 to 4 weeks.
Underwriting approach: New Silver accepts DSCR ratios as low as 0.75 and doesn't require prior investing experience, which makes it accessible for first-time investors.
Direct lender: New Silver funds its own loans, so the term sheet you receive comes from the lender that makes the final call.
Qualification: Minimum DSCR of 0.75, a 660 minimum credit score, up to 80% LTV, and loan amounts from $150,000 to $3 million. Eligible properties include 1 to 8-unit residential buildings, and short-term rentals qualify.
New Silver is one of the closest matches to Constitution Lending on requirements. The main difference is timing, since we typically close in 7 to 14 days compared with New Silver's 2 to 4 weeks.
Frequently Asked Questions
Can you refinance a BRRRR property before it's rented?
Often, yes. Many DSCR lenders will qualify a vacant property using market rent from the appraisal instead of a signed lease. Some require a lease for cash-out refinances, and most have seasoning requirements, so confirm both with your lender before planning the refinance.
How do you calculate your debt service coverage ratio?
Divide the property's monthly rent by its monthly debt payment, including principal, interest, taxes, insurance, and any HOA dues. For example, $2,400 in rent against a $2,000 payment gives a DSCR of 1.2. Anything above 1.0 means the rent covers the payment.
Do DSCR loans require a down payment?
Yes. Most DSCR lenders finance up to 80% of the purchase price, which means a 20% down payment. Some go up to 85% for borrowers with strong credit, while lower credit scores or weaker DSCRs can push the requirement to 25% or more.
Does refinancing the acquisition loan restart lien seasoning?
Usually not. Most lenders measure seasoning from the date you acquired the property, so refinancing doesn't reset that clock. Some lenders do look at how long the current loan has been in place before allowing a cash-out refinance, so check each lender's specific rules.
Who are the top DSCR lenders for real estate investors?
Commonly compared DSCR lenders include Constitution Lending, LendingOne, Griffin Funding, Kiavi, Lima One Capital, Visio Lending, Angel Oak, Easy Street Capital, RCN Capital, and New Silver. The best fit depends on whether you prioritize closing speed, low DSCR minimums, leverage, or loan size.
Who are the top DSCR lenders in 2026?
The leading DSCR lenders in 2026 include Constitution Lending, LendingOne, Griffin Funding, Kiavi (now owned by Figure), Lima One Capital, Visio Lending, Angel Oak, Easy Street Capital, RCN Capital, and New Silver. Compare them on closing speed, minimum DSCR, LTV, and loan amounts.